Buying a plot in Chennai can be a practical way to secure land for a future home or long-term investment without immediately taking on the cost of a completed property. The challenge is that land prices can require a sizeable upfront payment. EMI plots in Chennai offer an alternative by allowing buyers to spread the purchase cost through a loan or a developer-supported instalment arrangement. In 2026, buyers can find very different land prices across established neighbourhoods, OMR, GST Road and emerging suburban corridors, so choosing the right location matters as much as choosing the right financing option. Current listings illustrate this variation: for example, recent Kattankulathur listings on GST Road show plots around ₹3,500 – ₹4,500 per sq. ft.
Table of Contents
What Are EMI Plots in Chennai?
EMI plots in Chennai are residential plots purchased through a financing arrangement where the buyer repays the borrowed amount through regular instalments. Unlike buying a ready-to-occupy apartment, purchasing land gives you ownership of a plot that can potentially be developed later, subject to applicable planning and building approvals. You can explore available plots for sale in Chennai to compare plot options and locations. Financing may come from a bank or housing finance company, while some developers offer their own structured instalment plans.
Common features of EMI plot purchases include:
- Monthly repayment: The financed amount is repaid through scheduled EMIs.
- Down payment: Buyers generally contribute part of the purchase price from their own funds.
- Flexible plot sizes: Projects may offer different plot sizes based on availability.
- Future construction: Buyers can construct a home later, subject to approvals.
- Location-driven pricing: Plot prices vary based on location, connectivity, approvals and development.
How Do EMI Plot Schemes Work?
Select the plot: Compare location, size, access, approvals and total price.
Pay the initial contribution: This may include a booking amount or down payment.
Complete loan processing: The lender checks income, credit profile and property documents.
Loan disbursement: The approved amount is released as per the agreed terms.
Repay through EMIs: Monthly payments include principal and interest.
Plot Loan vs Developer EMI Plan
| Feature | Plot Loan | Developer EMI Plan |
|---|---|---|
| Provider | Bank/HFC | Developer |
| Interest | Charged by lender | Depends on developer terms |
| Property verification | Lender-led legal and technical checks | Depends on developer |
| Repayment | Formal loan EMI | Instalment schedule |
| Flexibility | Depends on lender | Depends on agreement |
| Key concern | Eligibility and interest cost | Agreement terms and project credibility |
Chennai Plot Prices in 2026
There is no single Chennai plot price in 2026 because land values vary significantly by location, connectivity, approvals, infrastructure and neighbourhood development. Established areas such as Anna Nagar and Velachery command substantially higher rates, while developing corridors such as Sriperumbudur and Oragadam offer relatively lower entry points. The figures below are indicative market rates and should not be treated as official government guideline values or guaranteed transaction prices.
| Chennai Location/Corridor | Indicative 2026 Plot Rate | General Positioning |
|---|---|---|
| Sriperumbudur | ₹1,500 – ₹2,400/sq. ft. | Emerging/industrial |
| Oragadam | Around ₹2,350/sq. ft. | Emerging/industrial |
| Kattankulathur/Potheri | ₹3,500 – ₹4,500/sq. ft. | GST Road |
| OMR/Kelambakkam | ₹3,500 – ₹6,500+ per sq. ft. | Mid-range to premium |
| Sholinganallur | ₹10,500 – ₹13,000/sq. ft. | Established IT corridor |
| Velachery | ₹11,500 – ₹13,550/sq. ft. | Established residential |
| Anna Nagar | ₹25,000 – ₹34,000/sq. ft. | Premium |
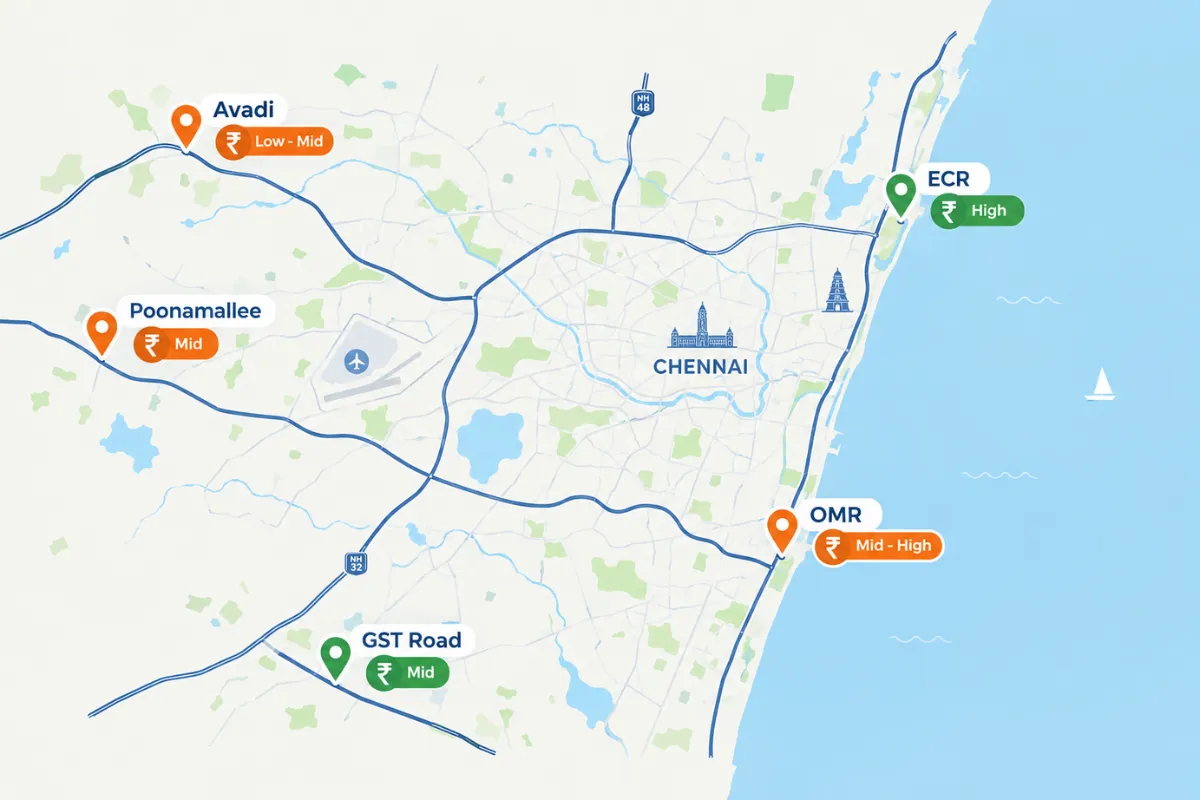
Plot Prices by Major Chennai Corridors
| Chennai Location/Corridor | Indicative 2026 Plot Rate | General Positioning |
|---|---|---|
| Sriperumbudur | ₹1,500 – ₹2,400/sq. ft. | Emerging/industrial |
| Oragadam | Around ₹2,350/sq. ft. | Emerging/industrial |
| Kattankulathur/Potheri | ₹3,500 – ₹4,500/sq. ft. | GST Road |
| OMR/Kelambakkam | ₹3,500 – ₹6,500+ per sq. ft. | Mid-range to premium |
| Sholinganallur | ₹10,500 – ₹13,000/sq. ft. | Established IT corridor |
| Velachery | ₹11,500 – ₹13,550/sq. ft. | Established residential |
| Anna Nagar | ₹25,000 – ₹34,000/sq. ft. | Premium |
These ranges are directional. Actual prices can differ even within the same locality based on road width, facing, plot dimensions, title, approvals and surrounding development.
What Affects Plot Prices in Chennai?
- Location and connectivity: Proximity to major roads, workplaces and public transport can increase demand.
- Approval status: Properly approved layouts can offer greater buyer and lender confidence.
- Road width: Wider roads generally improve access and development potential.
- Plot dimensions: Well-proportioned plots are easier to plan and construct.
- Neighbourhood development: Schools, hospitals, shops and communities influence demand.
- Flood risk: Check drainage, flooding history and nearby water bodies.
- Title quality: Verify ownership and property documents before paying.
Popular Areas to Buy EMI Plots in Chennai
The best place to buy an EMI plot in Chennai depends on your budget, work location, future plans and expected appreciation. South Chennai benefits from the OMR employment corridor, while GST Road offers diverse suburban locations. West Chennai and industrial corridors such as Sriperumbudur and Oragadam can provide comparatively lower entry prices. Notable plot-buying corridors in 2026 include OMR, Kelambakkam, ECR, GST Road and Sriperumbudur, although prices and project quality vary. For more information, explore best areas in Chennai.
When comparing locations, don’t ask only, “How cheap is the plot?” Consider “What will make people want this location five or ten years from now?” Connectivity, employment, infrastructure, schools, retail and residential demand can influence long-term value.
- For established demand: Consider Velachery, Sholinganallur and mature southern neighbourhoods.
- For IT corridor access: OMR and surrounding areas can be relevant.
- For lower entry prices: Sriperumbudur, Oragadam and selected GST Road suburbs may offer affordable options.
- For premium positioning: Selected ECR and established southern neighbourhoods command higher land values.
West Chennai and GST Road
West Chennai and the GST Road belt offer varied land options as development expands into suburban areas. Kattankulathur and Potheri, for example, show residential plot listings around ₹3,500 – ₹4,500 per sq. ft. GST Road also connects several employment, education and industrial destinations. Buyers should compare access roads, public transport, nearby development and infrastructure rather than treating the entire corridor as one market.
South Chennai and OMR
OMR remains a major employment-led residential corridor. Plot prices vary between established locations near IT hubs and developing areas toward Kelambakkam. Indicative rates around ₹3,500 – ₹6,500+ per sq. ft. can help buyers compare plot size, commute and monthly repayment.
Emerging Areas for Affordable Plots
If your priority is affordable land in Chennai’s wider growth region, consider:
- Sriperumbudur: Lower entry prices and industrial demand.
- Oragadam: Manufacturing-led development potential.
- Outer GST Road: Developing residential communities and plotted projects.
- Outer OMR/Kelambakkam belt: Balance of affordability and connectivity.
How Much Does an EMI Plot Cost in Chennai?
The total cost of an EMI plot depends mainly on plot size, price per sq. ft. and financing structure. For example, a 1,200 sq. ft. plot priced at ₹3,500 per sq. ft. has a basic land value of ₹42 lakh before registration, taxes, development charges and other costs. If 70% is financed, the loan amount would be ₹29.4 lakh, leaving ₹12.6 lakh towards the land-price contribution. The actual down payment depends on the lender, property and borrower profile.
Here are a few simple examples:
- 1,000 sq. ft. × ₹2,500/sq. ft. = ₹25 lakh
- 1,200 sq. ft. × ₹3,500/sq. ft. = ₹42 lakh
- 1,200 sq. ft. × ₹4,500/sq. ft. = ₹54 lakh
- 1,500 sq. ft. × ₹5,000/sq. ft. = ₹75 lakh
- 2,400 sq. ft. × ₹4,500/sq. ft. = ₹1.08 crore
These figures represent land value only. Registration, legal verification, development charges and financing costs can increase the overall cash requirement.
Plot EMI Calculation Example
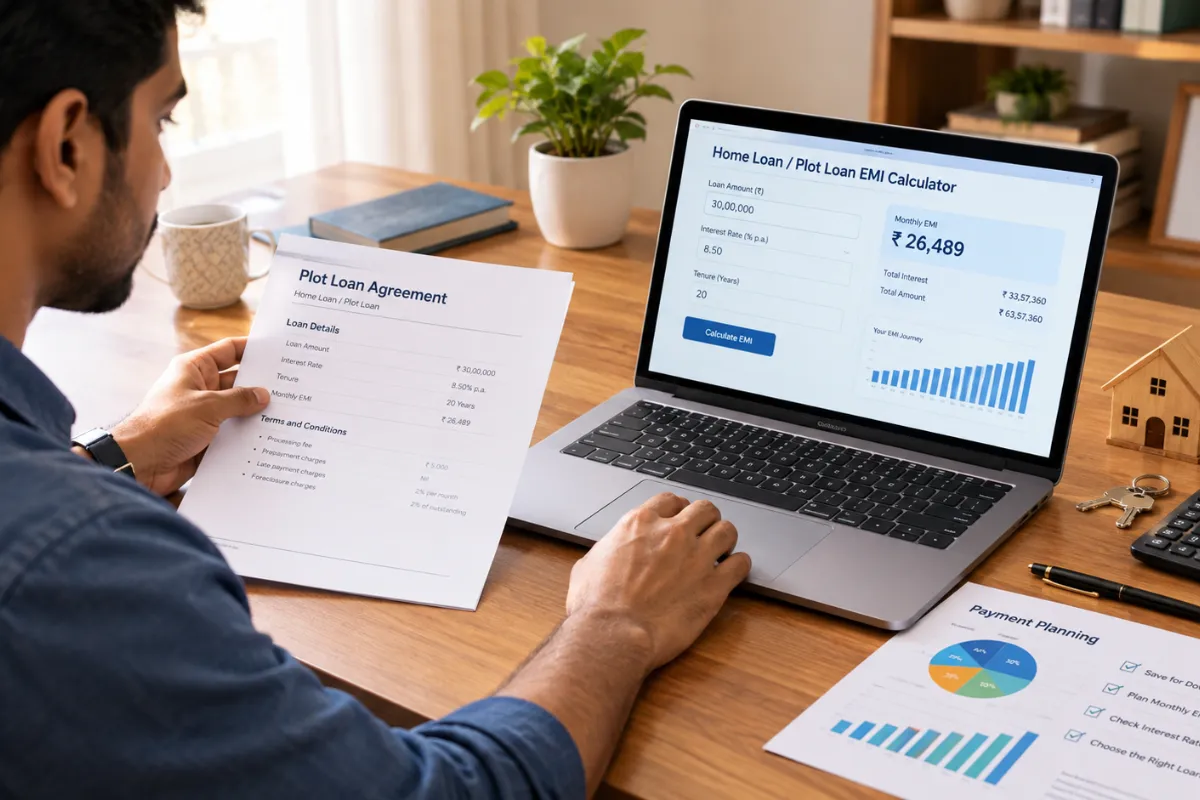
Assume a hypothetical ₹30 lakh plot loan at 9% annual interest for 15 years. The monthly EMI would be approximately ₹30,428. Total repayment would be about ₹54.77 lakh, including roughly ₹24.77 lakh in interest.
This shows why buyers should compare both the monthly EMI and total repayment. Actual costs depend on the lender’s rate, tenure, loan amount and applicable charges.
EMI Options and Plot Loan Eligibility
There are two common routes for buying land on instalments: formal plot loans and developer payment plans. A plot loan involves a financial institution evaluating the borrower and property, while a developer plan follows an agreed instalment schedule. Developer plans may appear simpler, but buyers should review cancellation terms, late-payment charges, possession conditions and refund policies. Property approvals and legal status can also affect financing.
Before shortlisting a plot, review your income, existing EMIs, credit history and available down payment. Calculate a comfortable EMI rather than borrowing the maximum amount available.
- Check your credit profile before applying.
- Maintain funds for the down payment.
- Keep separate funds for registration and transaction expenses.
- Compare interest rates and processing charges.
- Check lender rules for the specific plot and location.
- Keep sufficient income available for emergencies.
Bank and Housing Finance Plot Loans
Banks and housing finance companies may finance eligible residential plots subject to their policies. Lenders can conduct legal and technical checks covering title, approvals, location, accessibility and intended use. Loan terms and eligibility can change, so obtain a current loan illustration directly from the lender.
Plot Loan Eligibility Requirements
- Stable income and employment or business history.
- Acceptable credit history and repayment record.
- Age within the lender’s permitted range.
- Adequate income after existing obligations.
- Satisfactory property documentation.
- Approved residential plot or layout status.
- Required identity, address and income documents.
- Ability to provide the required down payment.
Meeting borrower eligibility does not guarantee approval because the property must also satisfy lender requirements.
Down Payment and Loan-to-Value
Lenders may not finance the entire purchase price. For example, if 70% of a ₹42 lakh plot is financed, the loan would be ₹29.4 lakh and the buyer would contribute ₹12.6 lakh.
Also budget for:
- Registration and statutory charges.
- Legal verification.
- Processing or administrative charges.
- Development or maintenance charges.
- Site preparation and future construction.
Documents Required for a Plot Loan
The exact document list varies between lenders, but buyers commonly need personal, financial and property documents to process a plot loan. You can also review property ownership in Chennai to understand the key ownership and documentation aspects before applying for a plot loan.
- Identity and address proof.
- PAN and required tax-related documents.
- Salary slips and bank statements for salaried applicants.
- Income-tax returns and financial statements for self-employed applicants.
- Employment or business details.
- Existing loan statements, where applicable.
- Sale deed/title documents.
- Parent or previous title deeds, where required.
- Encumbrance Certificate.
- Patta and relevant land records.
- Approved layout documents.
- Planning permission or local authority approvals, where applicable.
- Sale agreement or allotment document.
- Property tax receipts or applicable records.
The lender may request additional documents after reviewing the property’s title chain. Buyers should also conduct independent legal verification rather than relying only on the developer’s document checklist.
CMDA, DTCP and RERA Approval for Plots
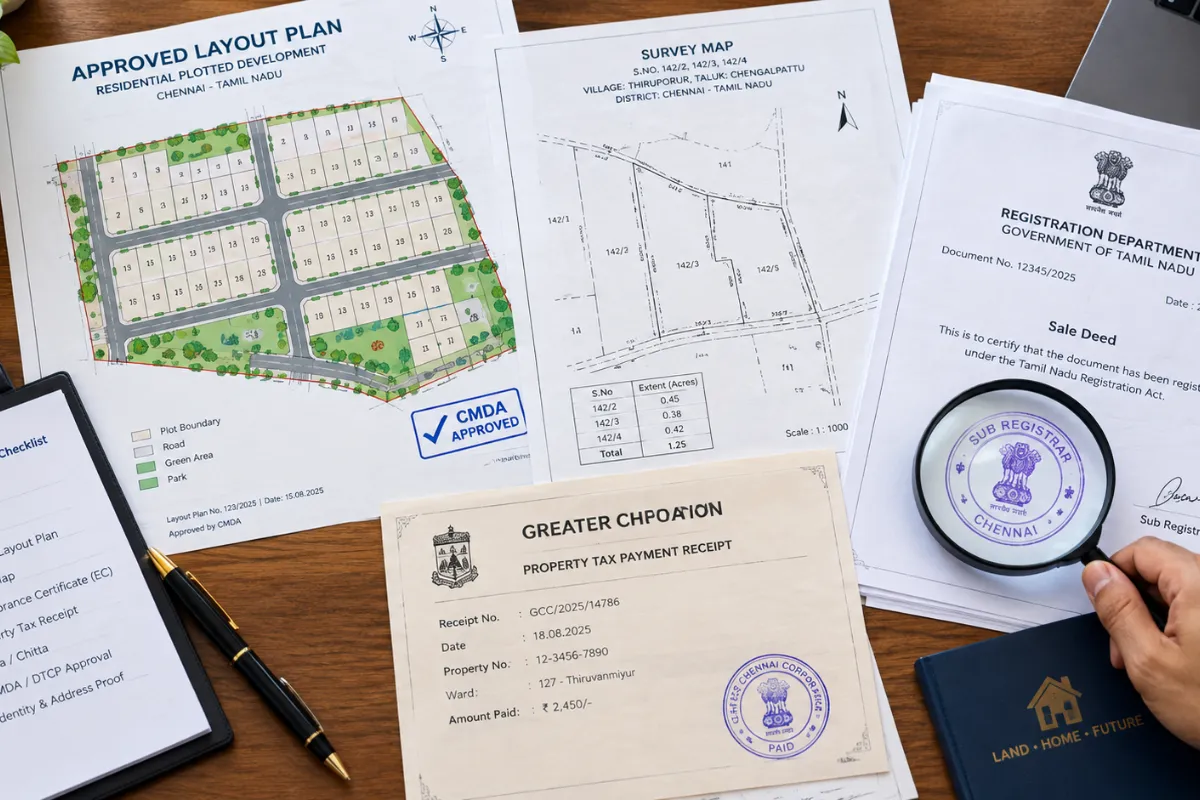
Approval is one of the most important checks when purchasing a plot in Chennai. A low-priced or attractive layout is not automatically a safe investment. Buyers should verify the relevant planning approval, legal transferability, access roads and whether the project requires registration under the applicable real-estate regulatory framework.
Planning approval should not be treated as a substitute for title verification. Buyers should examine the actual approval document, survey numbers, roads, reserved areas and permitted land use before proceeding.
CMDA and DTCP Approval
Within the Chennai Metropolitan Area, CMDA is a key planning authority, while DTCP applies to areas under its jurisdiction. The applicable authority depends on the property’s location. Obtain the approval reference and approved layout plan instead of relying only on a brochure.
The approved layout should match the actual property, including survey numbers, plot number, road network and dimensions.
Does RERA Apply to Plots?
RERA can apply to qualifying plotted developments under the applicable regulations. Buyers should check whether the project requires registration with the Tamil Nadu Real Estate Regulatory Authority and verify the project’s registered details before booking.
How to Verify Plot Approvals
Confirm jurisdiction: Identify the applicable planning authority.
Check approval reference: Obtain the approval number and layout plan.
Match survey numbers: Verify the approved land parcels.
Check plot number: Confirm the plot appears in the approved layout.
Verify road access: Match roads with the approved plan.
Check title: Get independent legal verification.
Check encumbrances: Review the Encumbrance Certificate.
Check RERA: Verify registration where applicable.
Check water-body risk: Investigate restricted areas and flooding concerns.
How to Choose the Right EMI Plot
Choosing the right EMI plot is less about finding the cheapest land and more about balancing price, legality, location and future usability. First decide whether you want to build a home soon or hold the plot as a long-term investment. A cheaper plot far from established infrastructure may not provide the expected value, while an expensive location can make the EMI unnecessarily difficult to manage. If you are also considering other property options, explore flats for sale in Chennai before making your decision.
A practical selection process looks like this:
Set a total budget: Include land price, registration, transaction expenses and financing costs.
Fix a comfortable EMI: Avoid planning around the maximum loan amount available.
Choose the corridor: Compare GST Road, OMR, western suburbs and other suitable areas.
Compare actual rates: Check similar plots with comparable sizes, locations and approvals.
Visit the site: Inspect roads, drainage, surroundings and nearby development.
Verify documents: Complete legal and approval checks before paying a major amount.
Compare lenders: Review interest rates, tenure, processing fees and prepayment terms.
Plan future construction: Ensure the plot suits your intended house and planning requirements.
Think of the purchase as a three-legged stool: location, legal quality and affordability. If one is weak, the investment becomes less stable.
EMI Plot Buying Checklist
Before finalising an EMI plot in Chennai, use this checklist:
- Confirm the exact plot dimensions and area.
- Compare the price per sq. ft. with nearby properties.
- Verify CMDA/DTCP or applicable planning approval.
- Check RERA registration where applicable.
- Verify title and ownership.
- Obtain an Encumbrance Certificate.
- Check patta and relevant revenue records.
- Verify survey and subdivision numbers.
- Inspect road access and road width.
- Check drainage and flood/water-body risks.
- Confirm electricity and water availability.
- Calculate the complete EMI burden.
- Keep funds for registration and other charges.
- Use an independent property lawyer for due diligence.
Advantages and Risks of Buying a Plot on EMI
Buying land through EMI financing can make property ownership more accessible for buyers with regular income who do not want to wait years to save the full purchase price. The main benefit is financial flexibility: you can spread the acquisition cost over time while securing the land sooner. A plot also provides greater control over future construction, subject to approvals. However, land does not automatically appreciate. Location, approvals, access and surrounding development strongly influence its future value.
| Advantages | Risks |
|---|---|
| Lower immediate cash requirement | Interest increases total cost |
| Potential long-term appreciation | Prices can stagnate |
| Build later according to your needs | Construction costs may rise |
| Flexible choice of plot size | Legal/approval problems |
| Can diversify property ownership | Continuing EMI obligation |
Advantages of EMI Plot Purchases
- Manageable cash flow: Spread the purchase cost through monthly payments.
- Future construction flexibility: Build when your finances are ready.
- Potential appreciation: Good locations may benefit from development.
- Customisation: Plan your future home within applicable regulations.
- Early ownership: Financing can help secure land sooner.
Risks to Consider
- Interest cost: Total repayment can exceed the land price.
- Approval risk: Poor approvals can create legal problems.
- Title risk: Ownership disputes can affect the investment.
- Location risk: Weak development can reduce resale demand.
- Liquidity risk: Land may take time to sell.
- Flooding and access: Drainage and road issues can reduce usability.
- Future construction costs: Building later requires additional funds.
Frequently Asked Questions
Can I buy a plot in Chennai on EMI?
Yes, eligible buyers can purchase residential plots using a plot loan from a bank or housing finance company. Some developers may also offer direct instalment plans. Loan approval depends on the buyer’s financial profile and the property’s legal and planning status.
How much does an EMI plot cost in Chennai?
EMI plot prices in Chennai vary significantly by location, plot size, approvals and connectivity. Developing areas such as Sriperumbudur and selected GST Road locations generally have lower entry prices, while established areas and premium corridors cost more.
What is the minimum down payment for a plot loan?
The down payment varies by lender, property and borrower profile. Buyers should generally be prepared to contribute part of the purchase price from their own funds, while also budgeting separately for registration, legal and other transaction costs.
Are EMI plots in Chennai eligible for bank loans?
Eligible residential plots may qualify for financing if they meet the lender’s legal, technical and planning requirements. Banks may verify title documents, approvals, layout status, location and accessibility before approving a plot loan.
What approvals should I check before buying an EMI plot?
Check the applicable CMDA or DTCP approval, title documents, Encumbrance Certificate, patta and approved layout plan. Where applicable, also verify Tamil Nadu RERA registration before making a substantial payment.
Conclusion
EMI plots in Chennai can be an attractive option for buyers who want to secure land without paying the full purchase price upfront. The right choice depends on balancing the monthly EMI with the plot’s market value, while carefully considering location, approvals, title and future development potential. In 2026, buyers can find options ranging from affordable emerging corridors such as Sriperumbudur and selected GST Road locations to premium established neighbourhoods.
Before committing, compare properties, visit the site, verify approvals, complete independent legal checks and calculate the total cost of ownership. A properly documented plot in a well-connected growth corridor can support future construction or investment.